

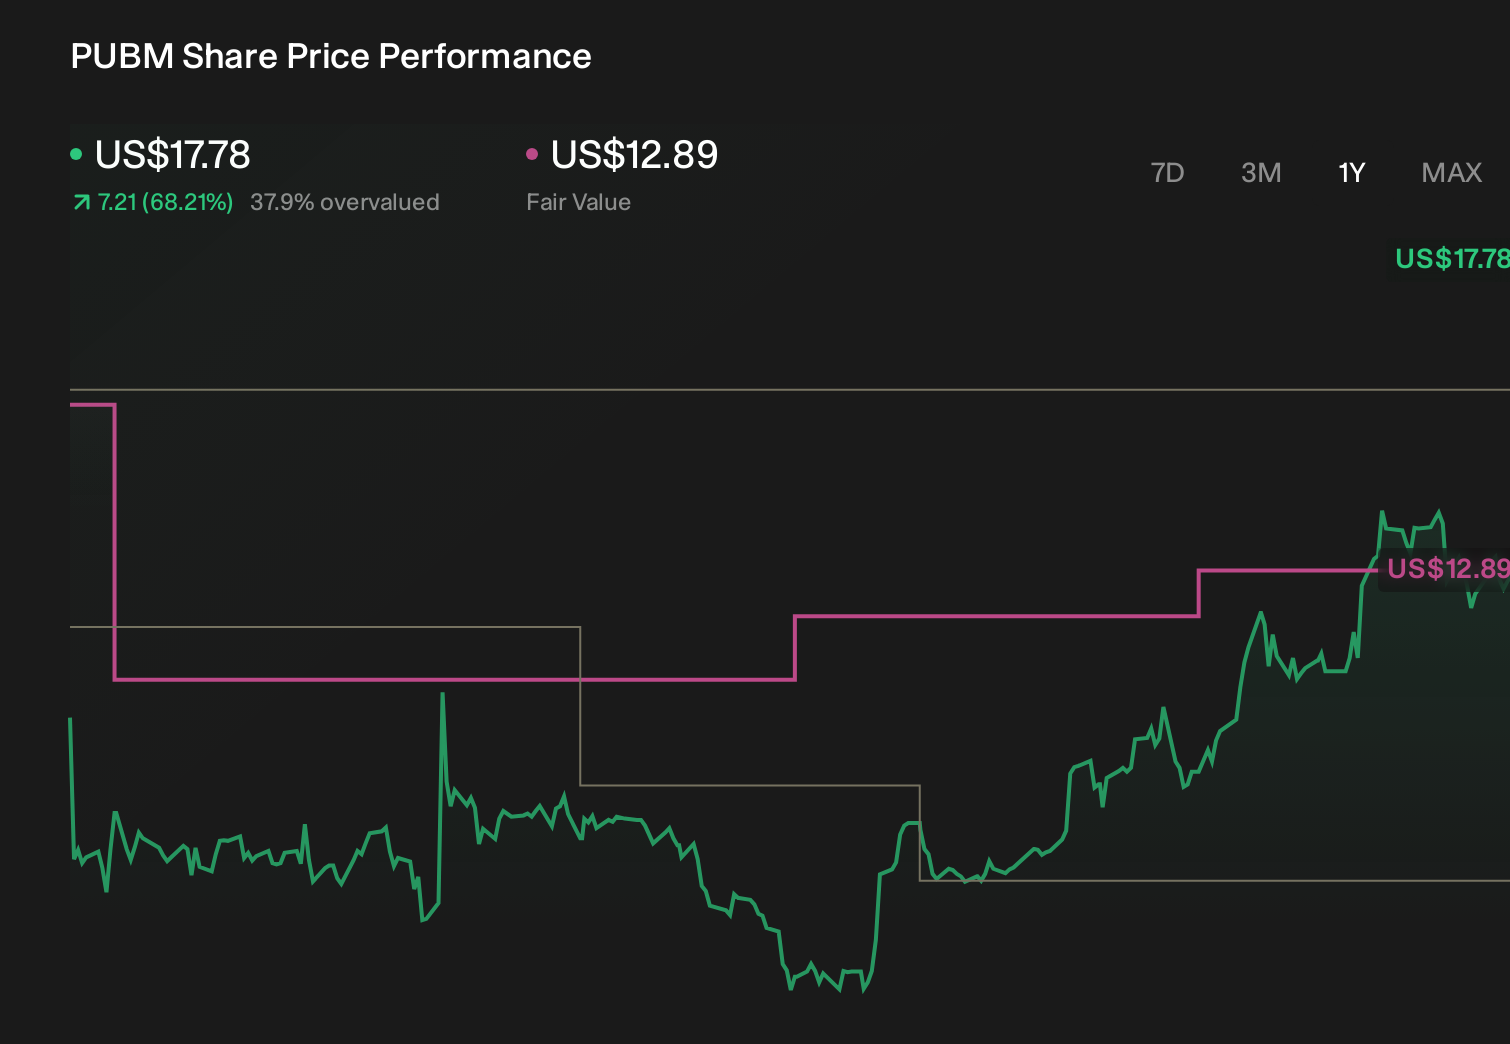
PubMatic (PUBM) saw its fair value estimate surge from US$12.89 to US$17.20 this week, driven by a robust second-quarter performance and a faster-than-expected return to revenue growth. The significant upward revision reflects a shift in analyst outlook, bolstered by a strategic pivot in the company’s revenue mix toward mobile app advertising and emerging digital formats.
Analyzing the Catalyst for Growth
The revised valuation follows a Q2 report that exceeded market expectations, signaling that PubMatic’s core business model is effectively navigating the current advertising landscape. Analysts point to the company’s ability to capture market share in mobile and high-growth formats as a primary driver for the improved long-term outlook. This shift suggests that the company is successfully diversifying its income streams beyond traditional desktop display advertising.
Understanding the PubMatic Narrative
Investment narratives are essential for connecting raw earnings data to broader market assumptions. By tracking how product launches, management guidance, and industry-wide shifts intersect, investors can gain a clearer picture of PubMatic’s trajectory. As new data becomes available, these models are updated to reflect the evolving risk profile and growth potential of the company.
Risk Factors and Market Outlook
While the momentum is currently positive, the investment case for PubMatic is not without hurdles. Analysts have flagged two specific risks that could influence future performance. Investors are encouraged to monitor these variables closely, as they may impact the stock’s ability to maintain its current valuation trajectory in the coming quarters.
To stay informed on how these risks evolve alongside the company’s business story, investors often utilize real-time monitoring tools. By keeping a close watch on fundamental data and analyst forecasts, market participants can better understand whether the current bullish sentiment aligns with their individual investment objectives and risk tolerance.