

Tutor Perini (TPC) stock continues to trade at a discount based on earnings multiples, despite a significant three-year rally that has left investors questioning if further upside remains.
Evaluating the Three-Year Surge
Tutor Perini has logged a very large 3 year gain, yet the valuation checks flag a more mixed picture. Investors are weighing a strong share price run against a market view that still screens the stock as undervalued on earnings based multiples.
The issue now is whether Tutor Perini’s current share price still leaves enough valuation upside to justify that past 3 year surge in returns.
P/E Ratios: The Construction Industry Benchmark
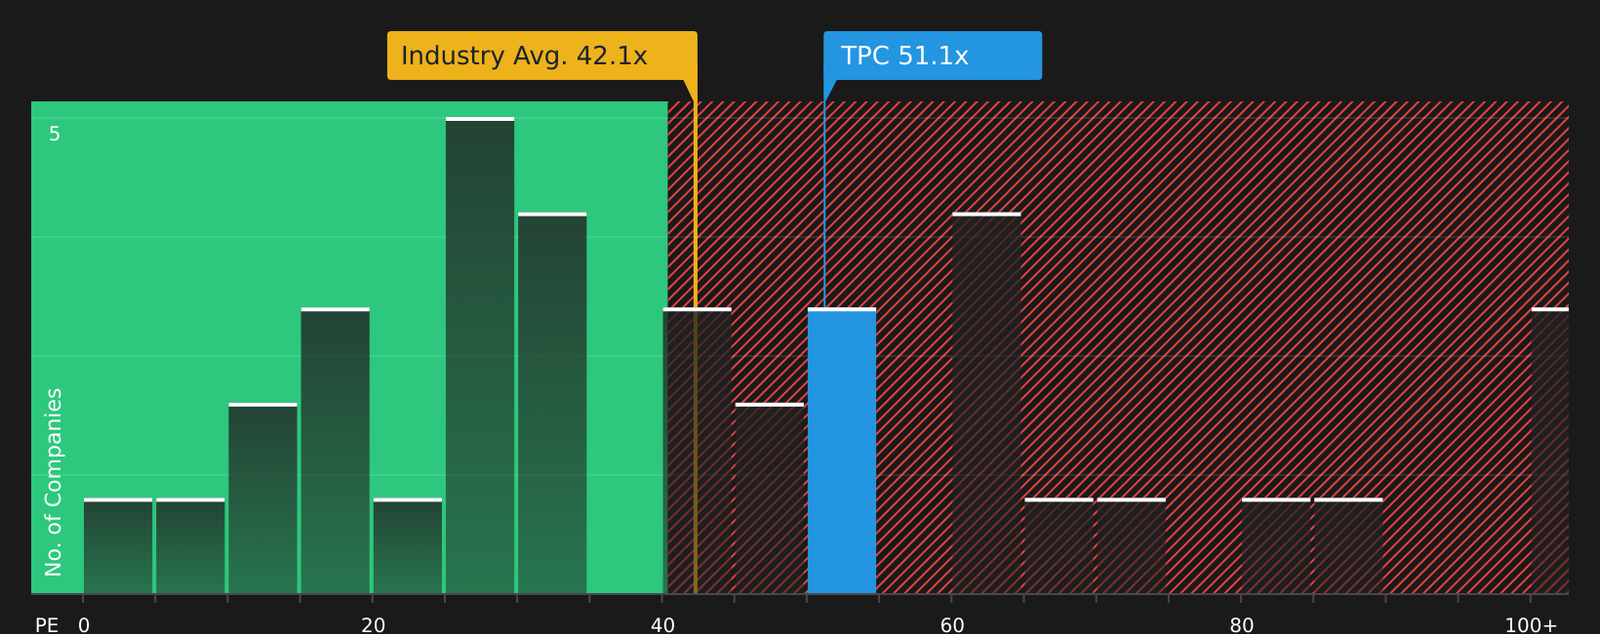
P/E is usually the cleanest way to compare earnings-based valuations across construction companies, and it is the preferred yardstick for Tutor Perini right now. The stock trades on a P/E of about 51.1x, compared with an industry average near 42.1x and a peer group average around 41.1x. This means the market is currently paying a higher price for each dollar of earnings than for many construction peers.
Assessing Fair Value Amid Legal Risks
Despite this premium to raw industry and peer averages, a more tailored fair P/E for Tutor Perini that factors in its profile comes out higher, at about 58.7x, so the current multiple sits below that reference point. Because the fair ratio is above where the shares trade today, Tutor Perini screens as undervalued on this earnings metric, even after recent headlines such as the additional US$42.4m judgment related to the Philadelphia hotel dispute have highlighted legal and project risks that some investors may be watching closely.
On the P/E multiple, Tutor Perini stock still screens as undervalued relative to the fair ratio implied by its earnings profile.
Navigating Future Earnings and Expectations
Simply Wall St Narratives for Tutor Perini sit between the P/E puzzle and real world expectations by spelling out which paths for earnings, margins and growth would need to play out for the stock to be worth materially more or materially less than today’s price. Each one links its number to a specific view of how Tutor Perini’s growth, profitability and project risks could evolve over time, giving you something concrete to revisit as fresh information comes through.
For Tutor Perini, the key message is that the stock still screens as undervalued on its tailored P/E multiple, even after a very large 3 year move. That discount exists alongside a mixed overall valuation profile and ongoing legal and project risks, so it is not a straightforward value story. What matters most from here is whether future earnings and cash generation prove resilient enough, and clean enough, for the current P/E to look conservative rather than a value trap that correctly reflects those uncertainties.