

Unum Group (UNM) announced a $3.8 billion long-term care reinsurance deal and a quarterly dividend of $0.505 per share this July, sparking debate over whether the stock is currently undervalued despite recent market momentum.
Momentum Meets Strategic Reinsurance
The recent dividend affirmation and the massive long-term care reinsurance move follow a period of significant growth for Unum Group. The company has posted a 90-day share price return of 14.13%, contributing to an impressive 5-year total shareholder return of 278.22%. This long-term trajectory highlights the resilience of the firm, even amidst short-term market pullbacks.
Valuation Tension: The P/E Perspective
From a traditional valuation standpoint, Unum Group faces scrutiny. Trading at a P/E ratio of 17.9x, the stock appears relatively expensive compared to the US insurance industry average of 12.3x and its peer average of 17.4x. For an insurer with forecast earnings growth of 17.36% and stagnant revenue growth of 0.7%, this multiple suggests the market is prioritizing current profitability over aggressive top-line expansion.
DCF Model Suggests Significant Upside
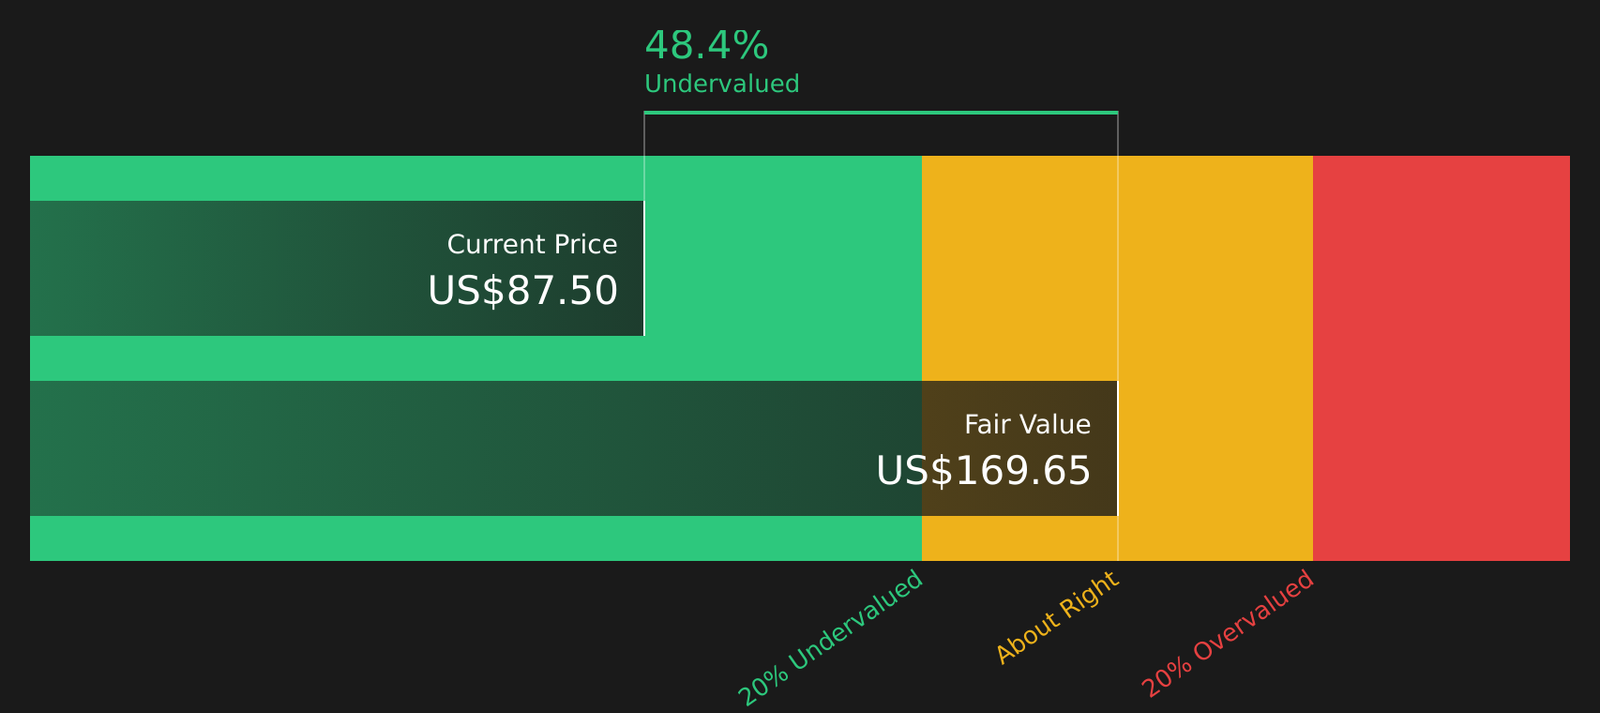
While the P/E ratio paints a picture of an overvalued asset, the Discounted Cash Flow (DCF) model offers a starkly different narrative. With a current share price of $87.50, the model estimates a fair value of $169.65 per share. This discrepancy suggests the stock could be trading at a 48.4% discount to its intrinsic value.
Explore the SWS fair ratio for Unum Group
The Long-Term Care Risk Factor
The wide gap between the DCF valuation and the P/E-based market assessment likely stems from investor caution regarding long-term care exposure. The market may be applying a heavy risk premium, fearing that future demand for employer-provided benefits could shift or that the company’s underlying assumptions might be too optimistic.
Find out about the key risks to this Unum Group narrative.
Investment Outlook
Unum Group sits at a crossroads. While the DCF model signals substantial undervaluation, the market remains wary of long-term care uncertainties and the premium earnings multiple. Investors must decide whether the current market caution is a justified defensive stance or an overlooked opportunity. Conducting a thorough review of the company’s key rewards and warning signs remains essential as the financial picture continues to evolve.
Look into how the SWS DCF model arrives at its fair value.
Take a close look at the 3 key rewards and 2 important warning signs