

Core Scientific (CORZ) shares are under intense investor scrutiny as recent market volatility forces a re-evaluation of the company’s ambitious AI data center growth narrative against its current financial performance.
Performance Volatility and Market Momentum
Trading at $23.49, Core Scientific has experienced a complex sequence of returns. While the stock saw a minor 1.05% decline in the last 24 hours, it maintains a robust 9.61% gain over the past week and an impressive 46.90% year-to-date increase. Despite a 30-day pullback of 8.56%, the 1-year total shareholder return stands at 87.77%, highlighting significant underlying momentum.
The Fair Value Discrepancy
A primary point of contention among market participants is the valuation gap. Current models suggest a fair value of $32.05, placing the stock in “undervalued” territory relative to its last closing price. This optimistic valuation hinges on aggressive revenue expansion and a rapid transition from operational losses to profitability—a trajectory that mimics the growth profiles of established software industry leaders.
Risks to the AI Expansion Narrative
The bull case for Core Scientific is built upon its pivot toward AI data centers, but the thesis faces clear headwinds. The narrative remains vulnerable to execution risks regarding new infrastructure projects and a heavy operational reliance on CoreWeave as a primary customer. Any shift in this partnership or delays in data center deployment could significantly undermine the company’s forward-looking models.
Valuation Multiples vs. Growth Expectations
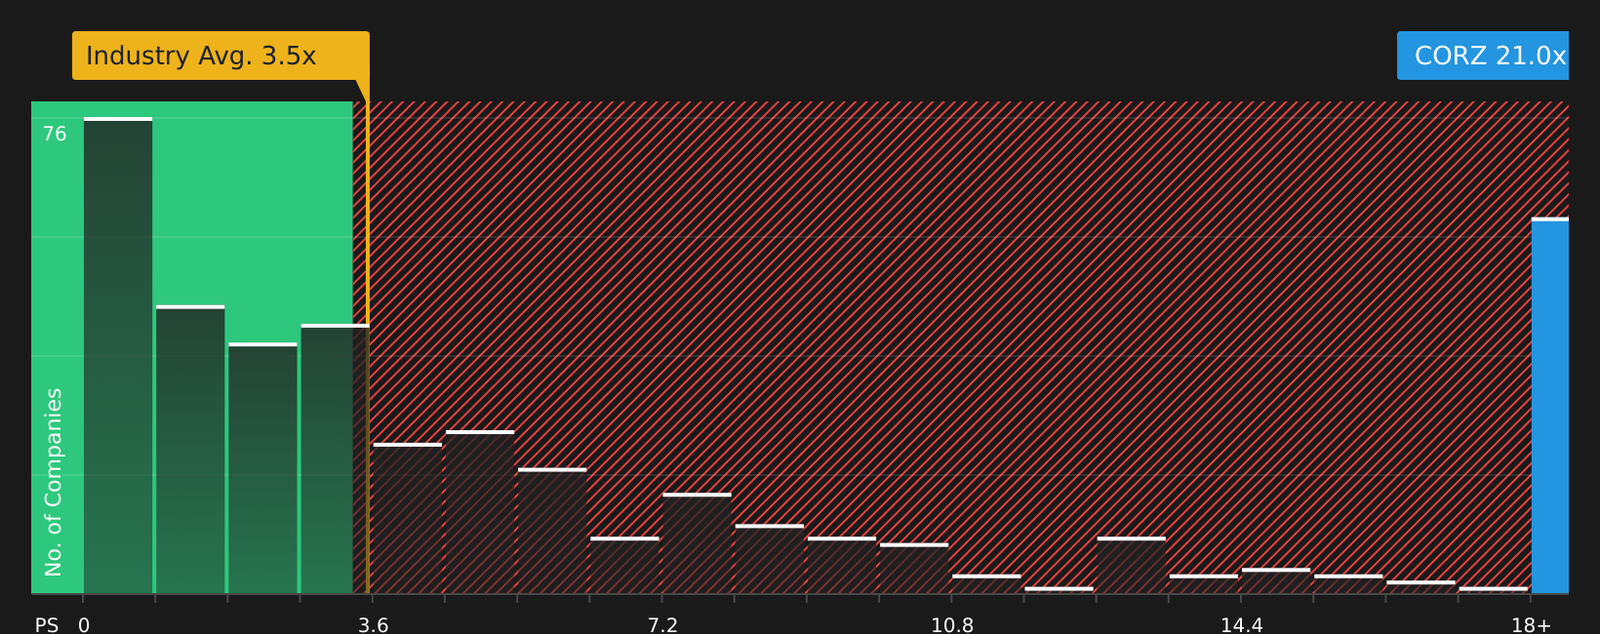
A critical divergence exists between the company’s growth story and its current trading multiples. Core Scientific currently commands a Price-to-Sales (P/S) ratio of 21x. This figure sits substantially higher than the US Software industry average of 3.5x and the broader peer average of 4.5x. Even when compared to a calculated “fair” ratio of 7.3x, the current valuation suggests significant downside risk should market expectations align more closely with industry standards.
Investors must weigh these conflicting signals: the allure of a high-growth AI infrastructure play versus the reality of premium valuation multiples that leave little room for operational error.