

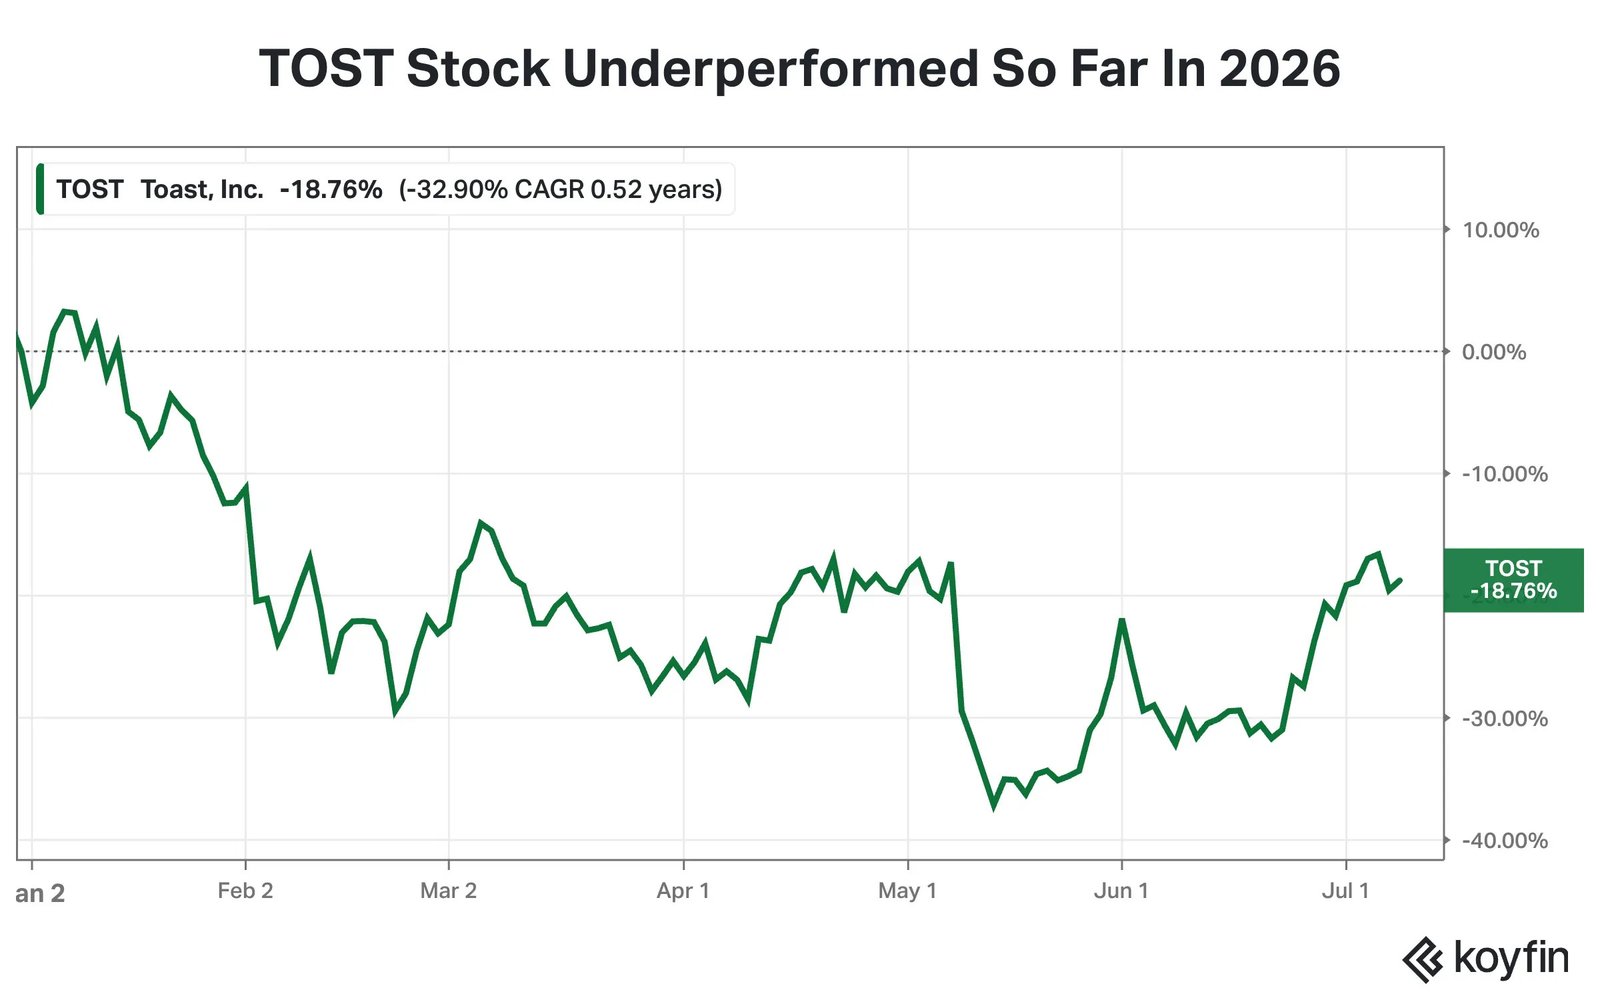
Toast Inc. (TOST) shares have surged over 15% in the past month, signaling a potential turnaround for the restaurant payments platform following a challenging start to the year. Goldman Sachs has officially upgraded the stock from ‘Neutral’ to ‘Buy,’ citing strong underlying fundamentals and a significant pathway for future growth.
Goldman Sachs Sets New $36 Price Target
Goldman Sachs has signaled strong confidence in Toast’s trajectory by raising its 12-month price target to $36, up from $30. This new valuation suggests an approximate 25% upside from the stock’s most recent closing price. Analysts at the firm view the current valuation as an attractive entry point, particularly following the company’s relative underperformance during the first half of the year.
Innovation and Market Expansion as Growth Drivers
The investment bank highlights Toast’s “best-in-class” product suite as a primary catalyst for future gains. Specifically, the introduction of AI-powered marketing tools, branded as ‘Toast IQ Grow,’ is expected to serve as a major accelerant for Software-as-a-Service (SaaS) average revenue per user.
Analyst Will Nance emphasized that Toast is successfully capturing market share through strategic expansion into retail, international markets, and enterprise sectors. Nance noted that the firm is particularly optimistic regarding the momentum currently building within the company’s retail division.
Resilient Consumer Spending Supports Outlook
Despite the stock’s nearly 35% decline over the past year, Nance pointed out that Toast’s core fundamentals remain robust. Consumer spending has shown resilience, maintaining positive momentum throughout the quarter—a trend that provides a favorable environment for Toast’s payment processing ecosystem to thrive in the medium term.
Wall Street and Retail Sentiment
Market sentiment is shifting in favor of Toast. According to Koyfin data, the Wall Street consensus reflects a bullish outlook, with 21 out of 30 analysts currently rating the stock as a ‘Buy’ or higher, while the remainder hold a ‘Hold’ rating. The average 12-month price target stands at $34.27, representing a potential 19% gain.
Retail investor interest is also spiking. Data from Stocktwits indicates that while message volume for the ticker jumped by 700% in a 24-hour period, sentiment has improved from ‘bearish’ to ‘neutral.’ Investors remain focused on whether the stock can maintain this momentum to validate the current bullish upgrade.