

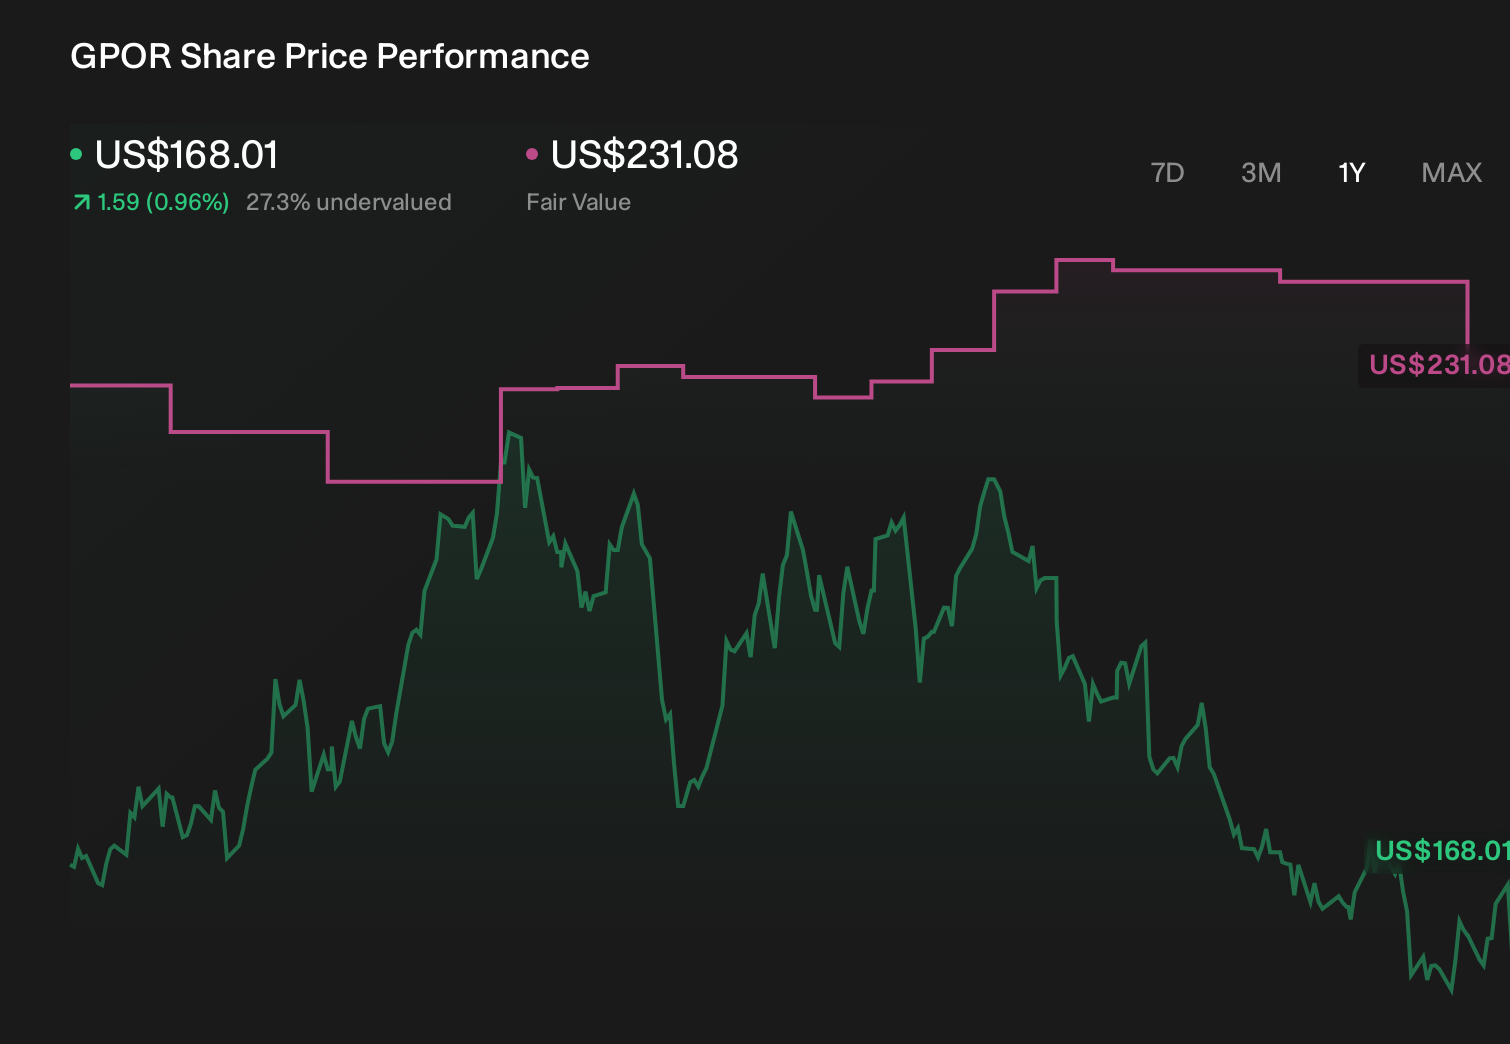
Gulfport Energy (GPOR) recently announced a leadership transition in its CFO position alongside updated 2026 production guidance, sparking debate over whether these shifts fundamentally alter the company’s investment thesis in the Utica and SCOOP basins.
Evaluating the Operational Strategy
Investors holding Gulfport Energy must align with its strategy of concentrated natural gas exposure in the Utica and SCOOP regions, underpinned by a focus on operational efficiency and capital returns. While the most recent quarterly results indicated a decline in production and earnings compared to the prior year, the company maintains stronger profitability on a year-to-date basis. The recent CFO transition and updated long-term guidance do not significantly disrupt the primary objective: meeting production targets while maintaining strict balance sheet discipline.
Analyzing 2026 Production Targets
The most critical update for shareholders is the full-year 2026 production guidance, which targets 1.030 to 1.055 Bcfe per day, alongside 18.0 to 21.0 thousand barrels per day of liquids. This forecast provides a clear benchmark for investors monitoring the sustainability of Gulfport’s concentrated asset base. Effectively, this guidance serves as the primary anchor for the company’s ongoing narrative regarding inventory management and operational efficiency.
Long-Term Risks and Valuation Discrepancies
Despite the operational focus, investors should remain cautious regarding the long-term risks associated with Gulfport’s heavy reliance on its core Utica and SCOOP plays. Current projections suggest a trajectory toward $1.7 billion in revenue and $542.9 million in earnings by 2029, a goal that necessitates a 7.3% annual revenue growth rate and a slight contraction from current earnings levels of $563.3 million.
Valuation remains a point of contention among market participants. Estimates from the Simply Wall St community reveal a significant divergence, with fair value assessments ranging from approximately US$231 to US$970. This wide spread underscores the volatility and the necessity of evaluating multiple independent perspectives when assessing Gulfport’s future performance and the potential 38% upside to its current market price.