

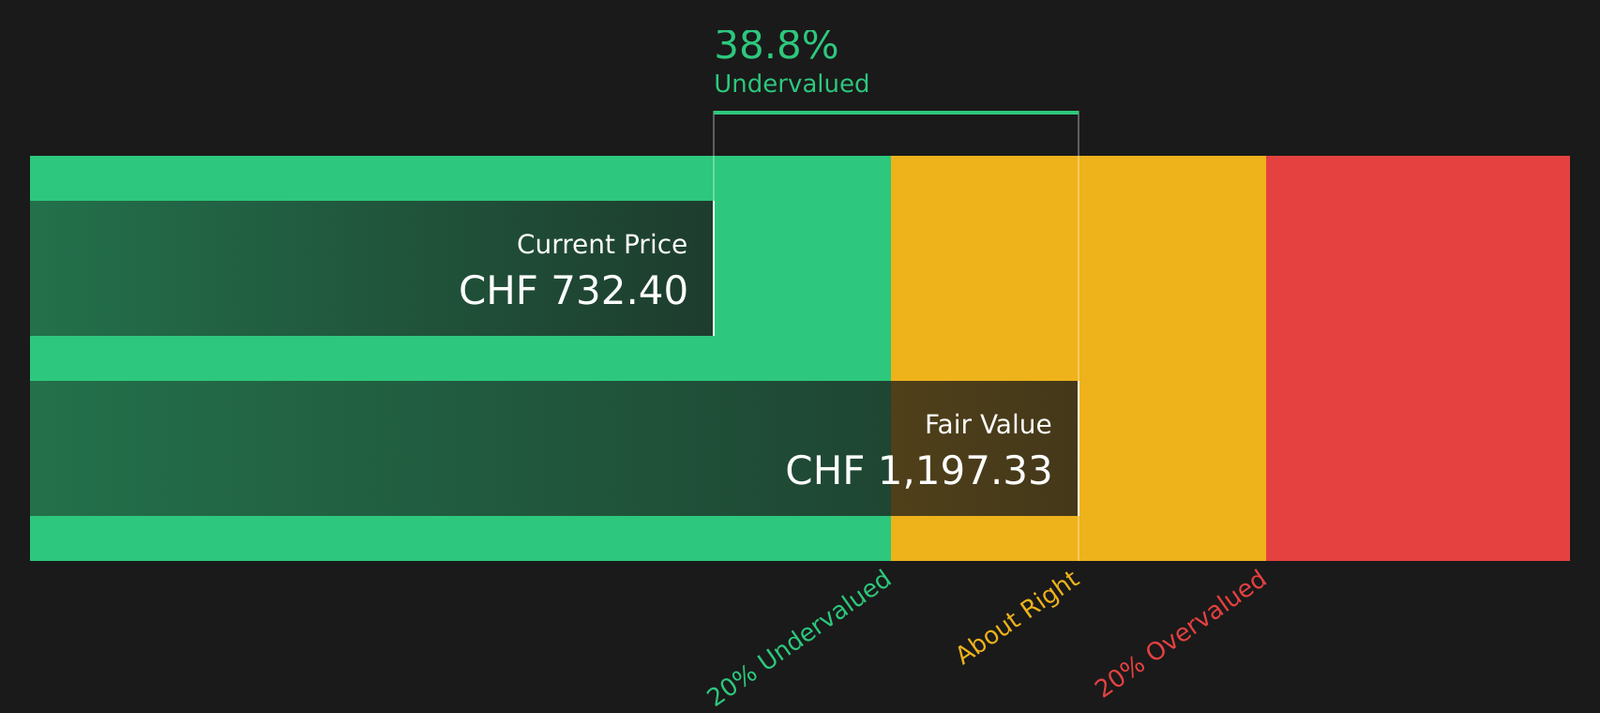
Partners Group Holding (SWX:PGHN) is currently trading at a significant discount to its intrinsic value, despite a challenging five-year period that saw shares decline by approximately 44.5%. With a recent uptick in share price performance, investors are now questioning whether the current valuation represents a genuine opportunity or a potential value trap.
Evaluating Excess Returns and Intrinsic Value
The Excess Returns model provides a deeper look at the company’s profitability relative to its equity capital costs. For Partners Group, the data reveals a robust return on equity, with a Book Value of CHF 84.83 per share and a Stable EPS of CHF 50.15. With the Cost of Equity estimated at CHF 4.15 per share, the company generates an Excess Return of CHF 46.00 per share, supported by an impressive 57.23% Return on Equity.
Based on these metrics, the intrinsic value of Partners Group Holding is estimated at approximately CHF 1,197 per share. This suggests the stock is currently trading at a 38.8% discount. A key driver behind this valuation is the recent EBITDA margin expansion at Foundation Risk Partners, fueled by AI-driven efficiencies, which continues to support future excess return projections.
P/E Ratio Analysis: Market Sentiment vs. Fundamentals
Because earnings power is vital for asset managers, the Price-to-Earnings (P/E) ratio serves as a critical benchmark. Partners Group currently trades at a P/E of roughly 15.0x, notably lower than the Capital Markets industry average of 16.8x and the peer group average of 18.2x.
When adjusting for the firm’s specific margins, scale, and risk profile, the fair P/E ratio is estimated at 18.4x. The gap between this fair multiple and the current trading price suggests that the market remains cautious. While the fundamentals indicate undervaluation, investor sentiment appears to be discounting the stock due to broader market uncertainties.
Navigating the Bull and Bear Cases
The investment narrative for Partners Group remains polarized, as reflected in community discussions regarding the stock’s future. The debate centers on whether the current discount is an attractive entry point or a reflection of late-cycle risks.
Investors are encouraged to explore the Full Bull Case to understand the potential for upside, or review the Full Bear Case to assess why some analysts perceive the stock as potentially overvalued. These perspectives help contextualize how future growth, margin stability, and earnings performance will dictate whether the current share price discount narrows over time.
The Verdict: Opportunity or Risk?
Partners Group Holding screens as undervalued under both the Excess Returns model and P/E ratio analysis. However, this discount may be viewed as compensation for perceived risks rather than a simple mispricing. The path forward depends on the firm’s ability to maintain high profitability through ongoing efficiency initiatives. Whether the market gains confidence in these operations will be the deciding factor in whether the current discount represents a long-term value play or a value trap.