

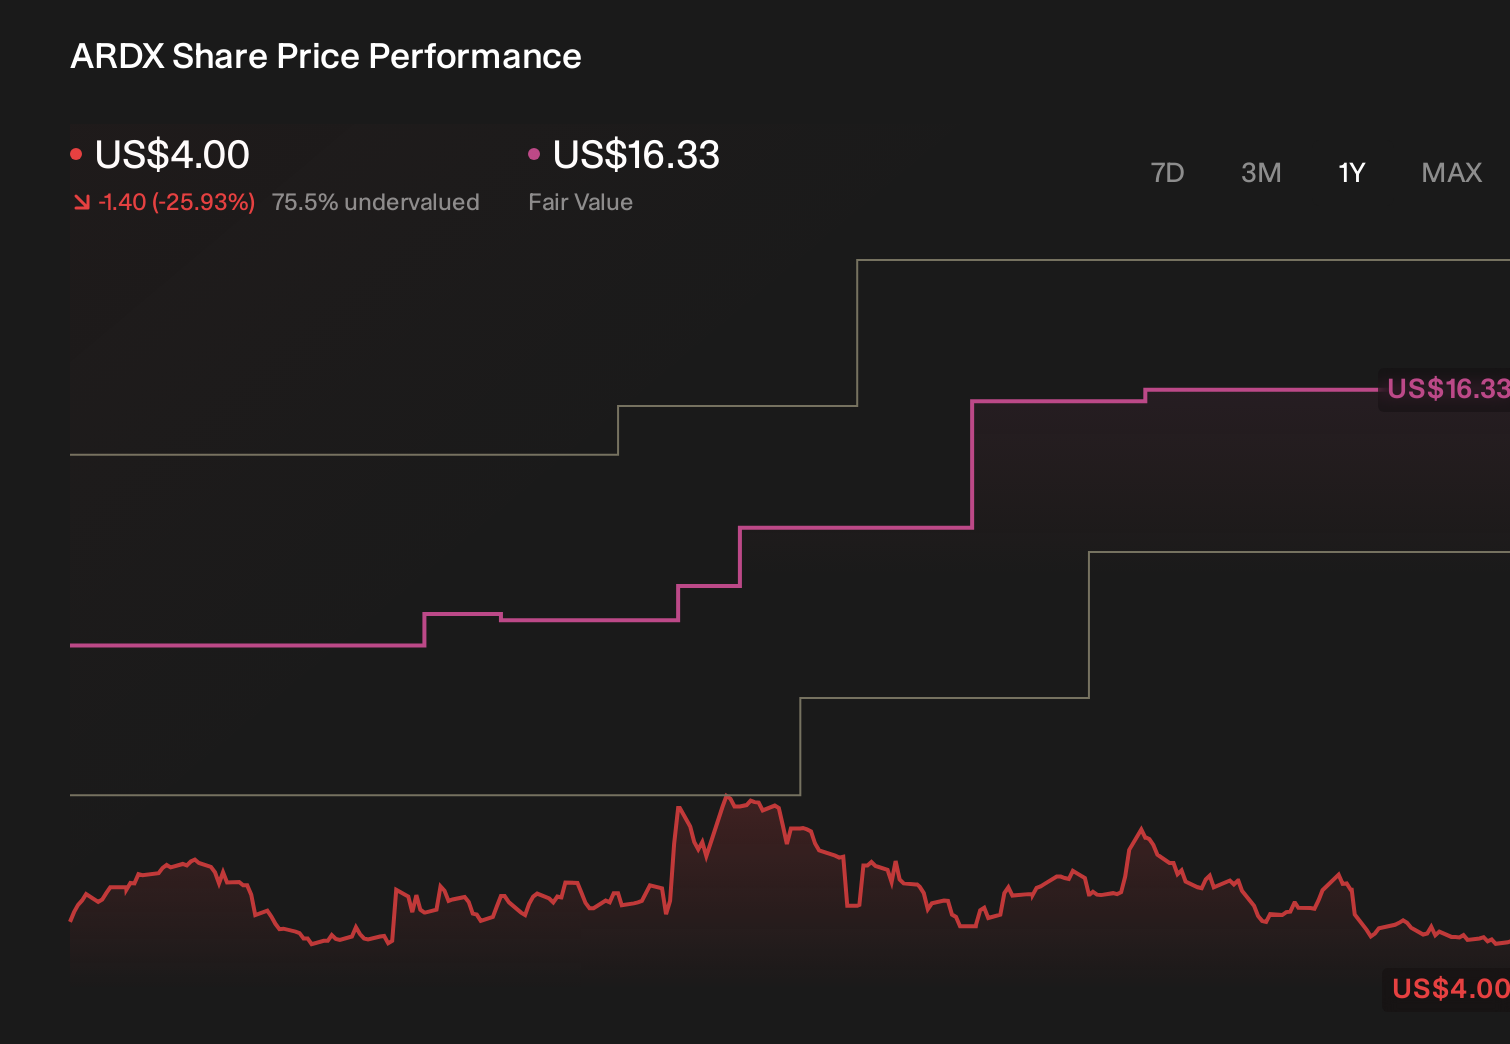
Ardelyx (ARDX) shares plummeted 19.7% today, despite the company raising its revenue guidance for IBSRELA and narrowing its overall financial losses, as investors grapple with ongoing concerns regarding product concentration and market access.
Commercial Execution vs. Portfolio Risk
To remain invested in Ardelyx today, you must believe that its specialized gastrointestinal and kidney franchise can successfully transition from narrowing losses to sustainable profitability. While the raised revenue guidance for IBSRELA highlights strong near-term commercial execution, it fails to mitigate the primary risk facing the firm: a heavy dependence on tenapanor-based products. This concentration leaves the company vulnerable to persistent reimbursement hurdles and legal uncertainties, particularly concerning XPHOZAH and Medicare coverage.
Tracking the 2026 Financial Roadmap
The company’s February 2026 guidance for IBSRELA and XPHOZAH serves as a critical benchmark for stakeholders. The recent upward revision of IBSRELA revenue expectations, paired with the reiteration of XPHOZAH targets, provides a clearer framework for investors. These figures—previously forecasted at US$410 million–US$430 million for IBSRELA and US$110 million–US$120 million for XPHOZAH—are now the primary metrics for determining whether the company’s commercial momentum is sufficient to offset its portfolio risk.
Long-Term Projections and Analyst Skepticism
Current company narratives project that Ardelyx could reach US$1.0 billion in revenue and US$317.0 million in earnings by 2029. Some models suggest these forecasts imply a fair value of US$16.33, representing a significant upside from current market pricing.
However, market skepticism remains high. Some analysts maintain a more cautious outlook, warning that even with improved IBSRELA guidance, the company faces an uphill battle if reimbursement setbacks continue to plague its narrow tenapanor portfolio. These critics suggest that earlier industry forecasts—which anticipated revenue of approximately US$935.2 million and earnings of US$186.3 million by 2029—may require significant downward adjustments in light of the latest operational results.