

Green Plains (GPRE) has surged 70.8% over the past year, yet the stock remains attractively priced at approximately US$15.09, signaling a potential disconnect between recent performance and current market valuation.
Evaluating the Price-to-Earnings Advantage
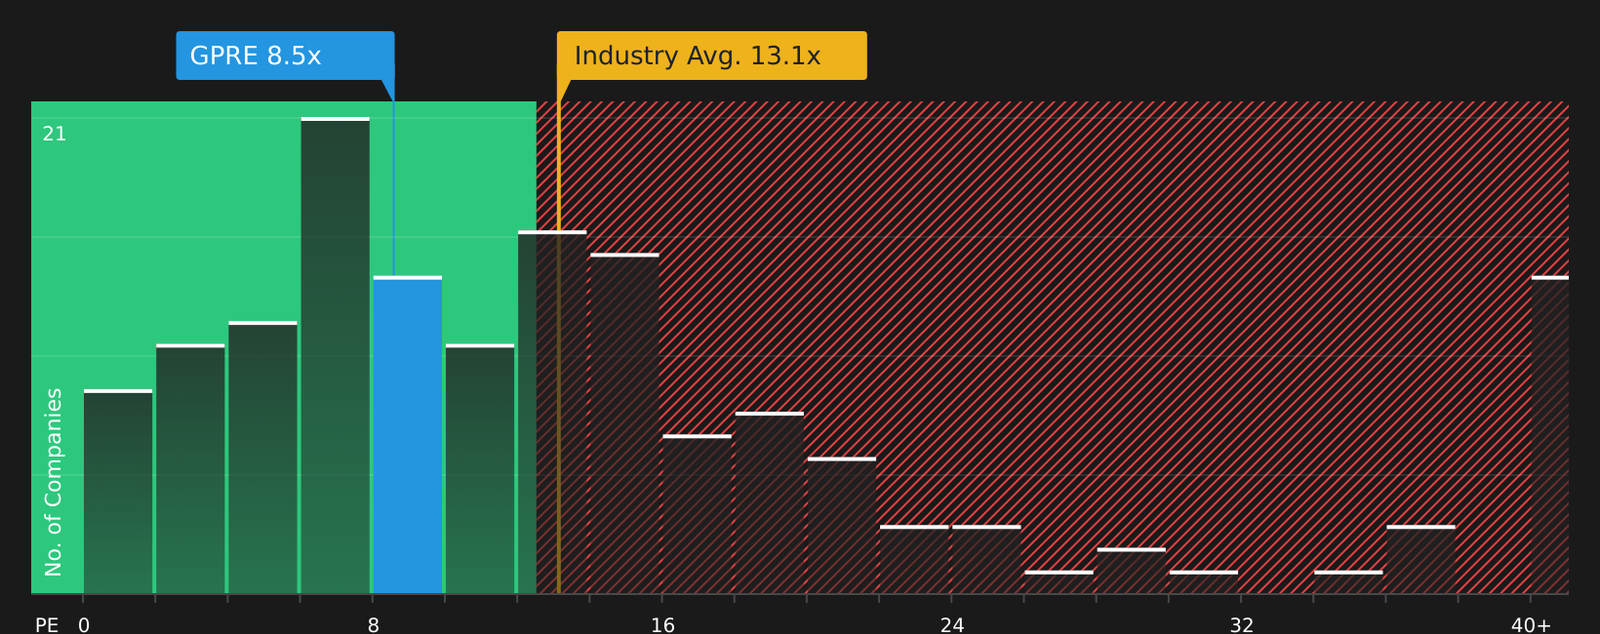
Investors assessing whether Green Plains is overextended after its massive rally should look closely at its valuation metrics. Currently, Green Plains trades at a price-to-earnings (P/E) ratio of roughly 8.5x. This figure sits notably below the broader Oil and Gas industry average of 13.1x and significantly lower than its peer group average of 20.8x. Based on these headline numbers, the stock appears to be priced more conservatively than many of its direct competitors.
The Case for Undervaluation
When applying a more nuanced yardstick that accounts for the company’s specific size, risk profile, and earnings characteristics, a “fair” P/E ratio for Green Plains emerges closer to 10.3x. Against this benchmark, the current 8.5x multiple suggests the market is applying a discount to the stock. For investors, this gap indicates that Green Plains still screens as attractively valued on an earnings basis, even following its recent period of share price strength.
On the P/E multiple, Green Plains stock appears undervalued compared with both its industry and its own fair ratio benchmark.
Navigating the Growth Narrative
Understanding the future of Green Plains requires looking beyond simple ratios. Specific paths regarding growth, margins, and earnings are essential to determining if the company is worth materially more or less than its current market price. These factors are dynamic, and as new information regarding the company’s profitability and risk profile emerges, the valuation narrative must be revisited.
Divided Market Sentiment
Investor sentiment regarding Green Plains remains polarized. One segment of the market is heavily focused on the company’s earnings potential supported by current government policy, while the other remains cautious, pointing to long-term demand risks associated with the ethanol industry.
Read the full Bull Case to see why Green Plains could be undervalued
Read the full Bear Case to see why Green Plains could be overvalued
Ultimately, Green Plains continues to screen as undervalued on both its P/E and tailored fair ratio metrics, even after a strong one-year return. The broader valuation checks suggest that the current discount reflects market caution rather than definitive overpricing. Moving forward, the core question for stakeholders is whether Green Plains can successfully convert its business model into consistent earnings and cash flow, or if long-term demand and policy risks will continue to justify a cheaper multiple.