

Ormat Technologies (ORA) has delivered a significant 64.4% share price gain over the past five years, but current valuation metrics suggest the stock may be trading at a premium rather than offering a bargain.
Evaluating Intrinsic Value via DCF
The core question for investors is whether Ormat’s current market price accounts for future growth or if it has outpaced the company’s intrinsic value. Using a Discounted Cash Flow (DCF) model—which projects future cash flows to estimate present value—presents a complex picture. Given that Ormat reported a free cash flow loss of approximately $403 million over the trailing twelve months, the model relies on the assumption that cash flows will recover and expand significantly over time.
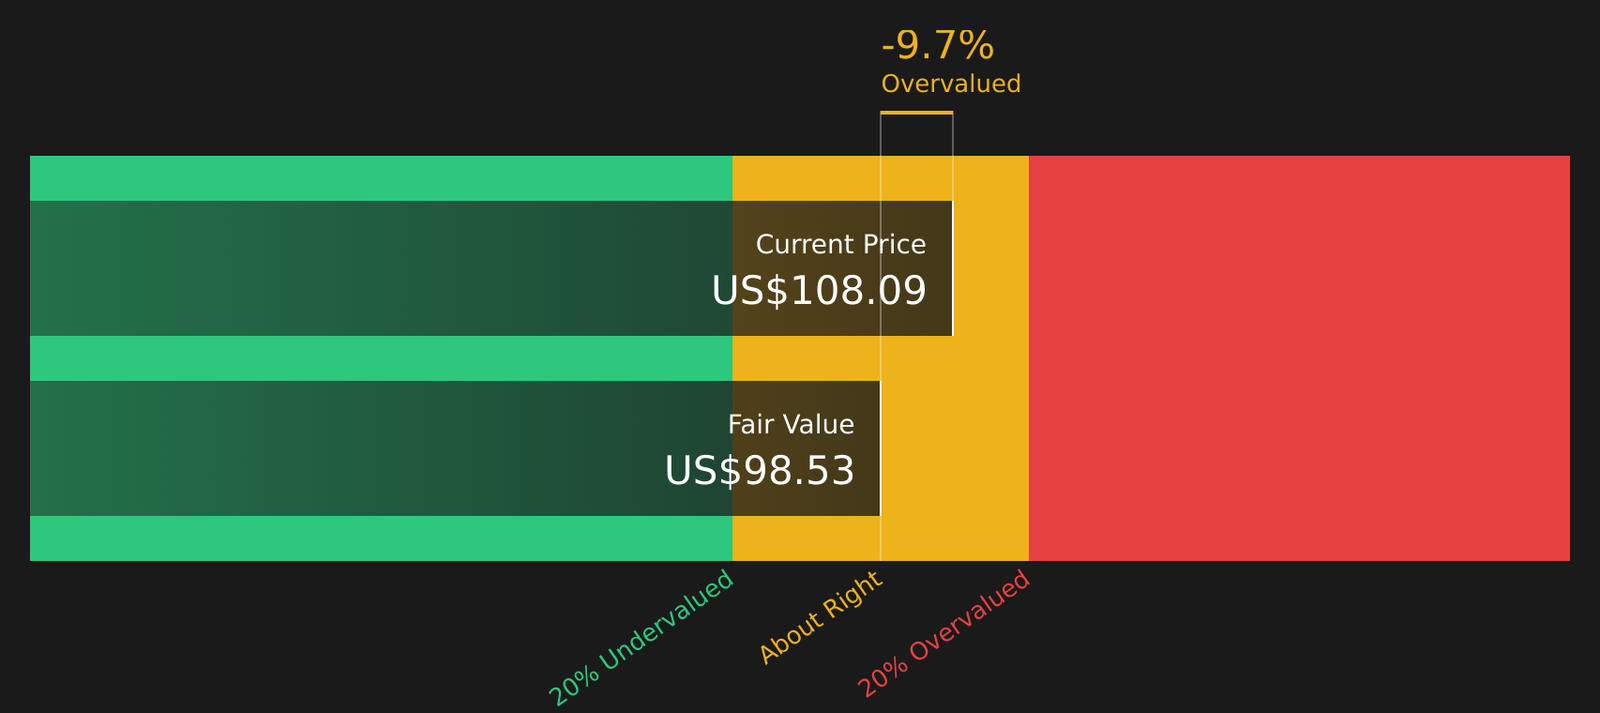
Based on these projections, the DCF model estimates an intrinsic value of about $99 per share. With the stock currently trading above this figure, it appears roughly 9.7% overvalued. However, the market’s willingness to pay this premium may be tied to Ormat’s Q2 2026 update and the company’s raised full-year revenue guidance.
The P/E Ratio Reality Check
Beyond cash flow models, the Price-to-Earnings (P/E) multiple provides a vital cross-check against actual reported earnings. Currently, Ormat Technologies trades at a P/E of approximately 52.5x. This figure sits substantially higher than the renewable energy industry average of 16.8x and the peer group average of 27.3x.
When adjusting for Ormat’s specific risk profile, margins, and scale, a fair P/E ratio would be closer to 25.1x. The fact that the stock is trading at more than double this benchmark indicates that investors are currently paying a significant premium for the company’s shares relative to its peers.
Future Execution Remains Key
The combination of a DCF model pointing to a value below the current share price and an earnings multiple that suggests significant overvaluation shifts the focus to future performance. The burden of proof now rests on Ormat Technologies to demonstrate the cash flow and earnings growth necessary to justify its current market valuation.
For investors, the path forward depends on whether the company’s recent revenue growth and energy storage performance can sustain the market’s current optimism. As new results arrive, monitoring these fundamental drivers will be essential to determine if the stock’s premium is supported by operational reality.