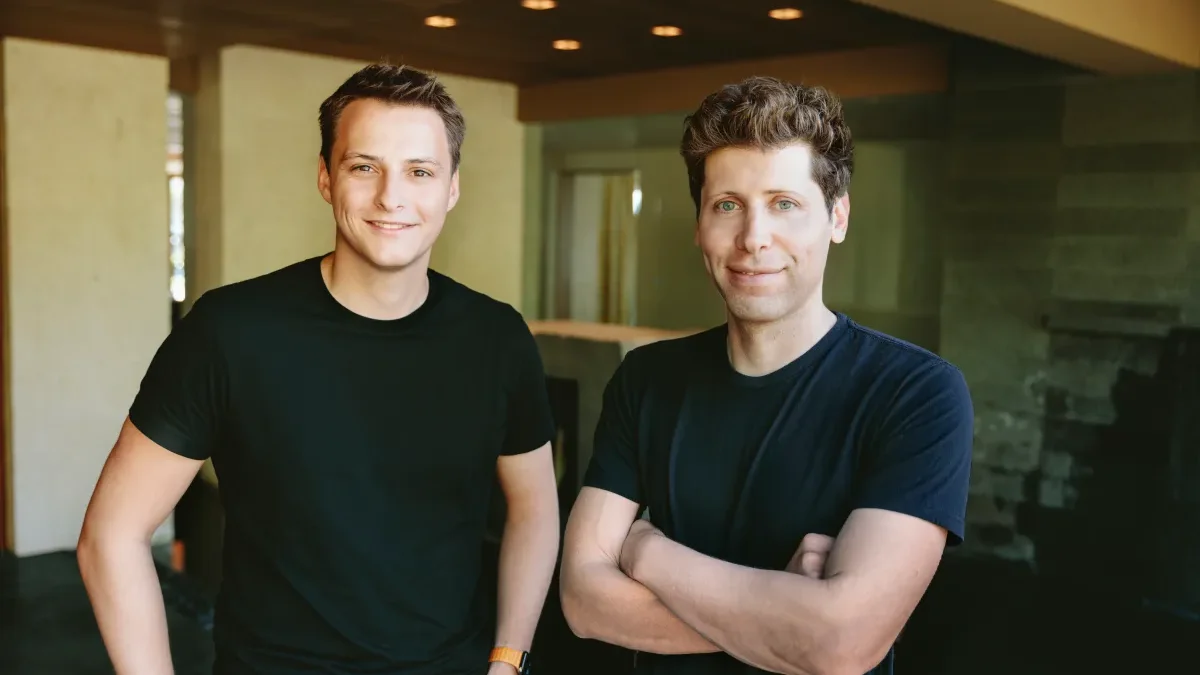
World, the online verification company co-founded by Sam Altman of OpenAI, has successfully raised $52.5 million through a strategic crypto token sale aimed at select investors.
Details of the Token Sale
Investors participated in a 12-month lockup sale for World’s token, known as WLD. This lockup period restricts buyers from selling or trading their tokens for an entire year, showcasing their “long-term commitment to World’s ongoing growth and utility,” as stated by the company in a press release issued on Friday.
Funding Allocation
The funds raised will be directed toward the World Foundation, a limited guarantee foundation based in the Cayman Islands, which has been established to oversee the expansion of World’s network.
Key Investors Involved
Leading the purchase is Pantera Capital, a venture capital firm that specializes in digital assets. Additional participants in the sale include Eightco Holdings, Bain Capital Crypto, Susquehanna Crypto, and Selini Capital, among others.
About the World Project
The World project is managed by Tools for Humanity (TFH), a startup located in San Francisco, led by CEO and co-founder Alex Blania, with Altman also as a co-founder.
Understanding World’s Unique Approach
World offers a distinctive service focused on online verification, providing access to tools designed to prove human identity. As artificial intelligence and bots increasingly shape online content, the demand for distinguishing between genuine humans and automated entities is set to rise. World aims to promote its World ID, an anonymous digital marker that confirms whether a human — rather than a bot or AI agent — is operating an account.
How to Obtain a World ID
To acquire a verified World ID, which represents the highest tier of verification within the platform, users must undergo an iris scan via an Orb, a metallic device that transforms a user’s iris into a unique cryptographic identifier. World’s Orbs can be found at their offices and have also been placed in partner stores worldwide.
Evolution of the Project
Initially launched as a more crypto-centric initiative under the name “Worldcoin” — the same name associated with the crypto asset involved in this recent funding round — users had the option to trade or store tokens using World’s app, which also functions as a custodial wallet. The company later rebranded to World amid a broader backlash against the cryptocurrency sector.
Recent Developments and Challenges
In April, the project unveiled a new version of its app and announced collaborations with companies such as Tinder, Zoom, and Docusign. However, despite its ambitious global vision, World has faced difficulties in scaling its operations and attracting consumer interest in its mission. In June, TFH conducted a series of layoffs.
Correction July 24: An earlier version of this article mistakenly claimed that World has a partnership with Ticketmaster. This is not the case, and we apologize for the error.